There are many misconceptions about the credit score needed to buy a house. Recently, it was reported that 24% of renters believe they need a 780-800 credit score to be considered for a mortgage. The reality is they are misinformed!
Only 25% of the Americans have a FICO® Score between 740 and 800. Here is the breakdown according to Experian:
16% Very Poor (300-579)
18% Fair (580-669)
21% Good (670-739)
25% Very Good (740-799)
20% Exceptional (800-850)
Randy Hopper, Senior Vice President of Mortgage Lending for Navy Federal Credit Union said,
“Just because you have a low credit score doesn’t mean you can’t purchase a home. There are a lot of options out there for consumers with low FICO® scores,”
There are many programs available with low or no credit score requirement. The Federal Housing Administration (FHA) now requires a minimum FICO® score of 580 if you want to qualify for the low down payment advantage. The US Department of Agriculture (USDA) does not set a minimum credit score requirement, but most lenders require a score of at least 640. Veterans Affairs (VA) loans have no credit score requirement.
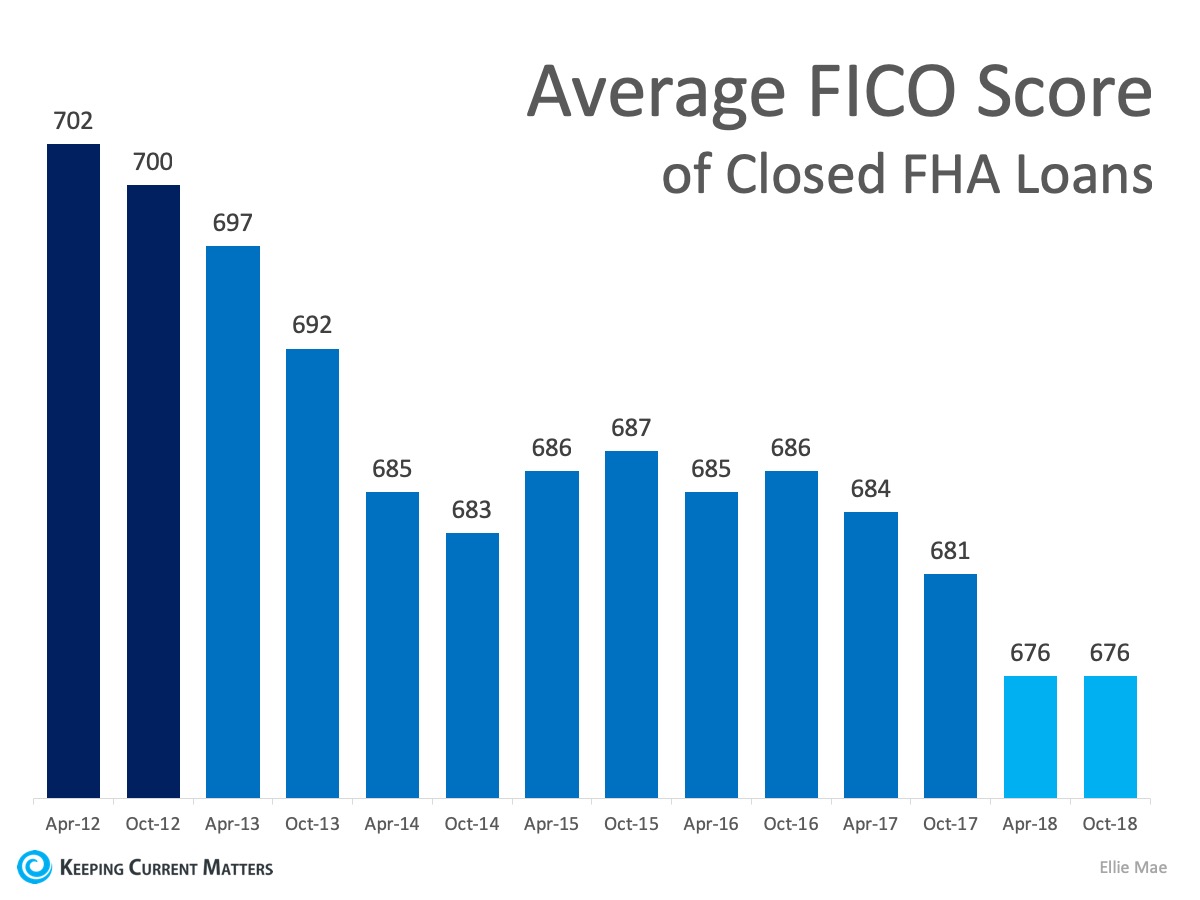
As you can see, none of them are above 700!
It is true that the average FICO® score for all closed loans in January was 726, but there are plenty of people taking advantage of the low credit score requirements. Here is the average FICO® Score of closed FHA Loans since April 2012 according to Ellie Mae:
As you can see, that number has been dropping for the last seven years. As a matter of fact, the average FHA Purchase FICO® Score reported in January 2019 was 675!
One of the challenges is that Americans are unsure about their credit score. They just assume that it is too low to qualify and do not double check. Credit.com confirmed that only 57% of individuals sought out their credit score at least once last year.
FICO® reported,
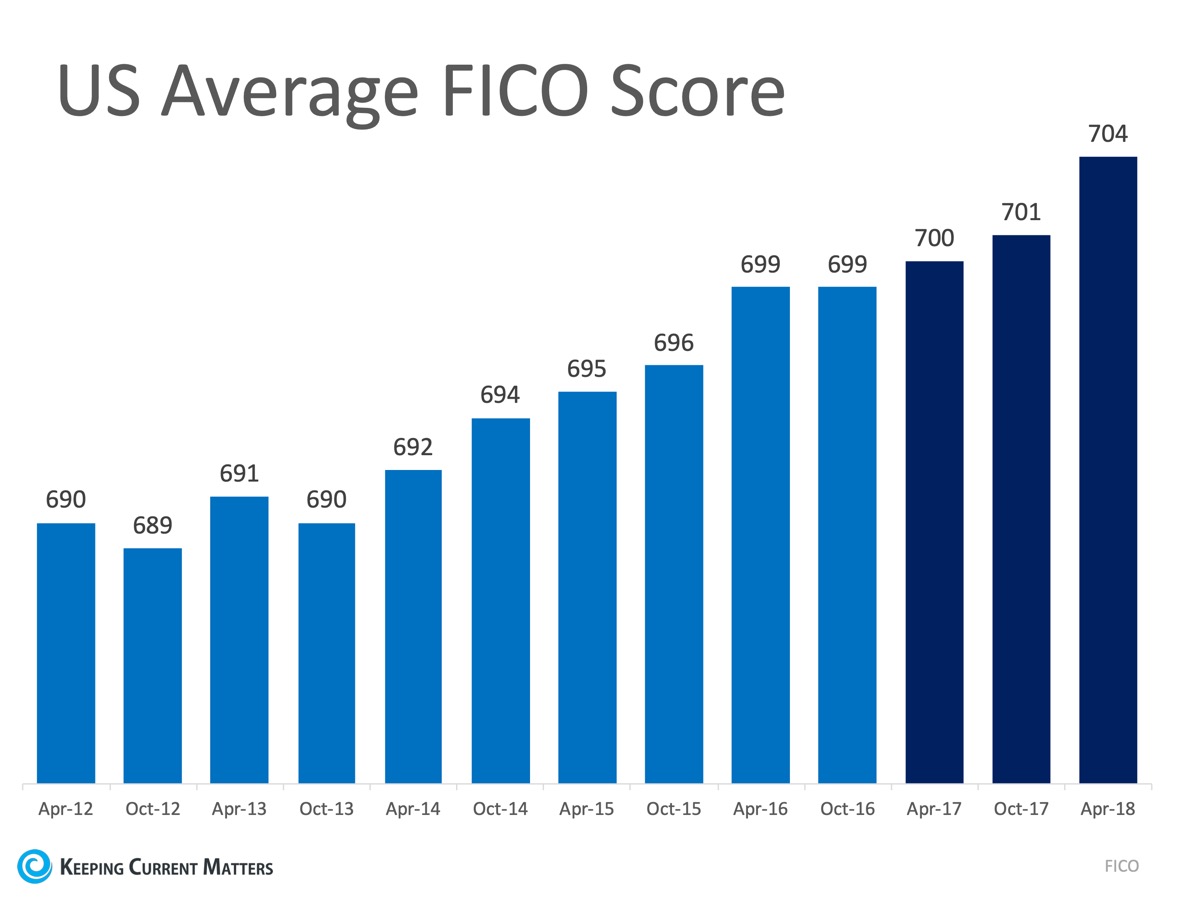
“Since October 2009, the average year-over-year FICO® Score has steadily and consistently increased, from a low of 686 in 2009 to the latest high of 704 as of 2018.”
Here is the increase in the average US FICO® Score over the same period of time as the graph earlier.
Bottom Line
At least 84% of Americans have a score that would allow them to buy a house. If you are unsure what your score is or would like to improve your score in order to become a homeowner, sit down with a real estate professional that can help you to set a path to reach your dream!
Mortgage rates have plummeted this week to levels not seen in over a year, offering borrowers the chance to save thousands of dollars in interest costs over the life of a home loan. So if you’ve been thinking about buying a house or refinancing your existing mortgage to take advantage of […]
Mortgages are a lot like cars: Even those who have one don’t always understand what’s going on under the hood. Whether you’re dreaming of your first house or living in your third, mortgages can seem complicated and a little scary. That’s why thousands of people punch mortgage-related questions into their […]
Sixty-four percent of American households own their home. If you’re making the transition from renter to homeowner, it’s a time to take your finances seriously. If you’ve decided to buy a home, what questions do you ask first? “How much can they afford. They should start asking their bank or […]